
Real-world asset tokenization is moving from proof of concept to institutional-grade applications. Multiple analytical institutions predict that the global market size for related assets could reach the hundreds of billions of dollars by 2034, driven by the resonance of three needs: compliance frameworks, on-chain settlement efficiency, and asset liquidity. This article outlines the core logic of an RWA tokenization crypto tutorial from a practitioner’s perspective: first explaining ‘why do it now,’ then breaking down ‘how to do it,’ and finally clarifying easily overlooked risks and compliance boundaries, helping teams build a complete cognitive framework before taking action.
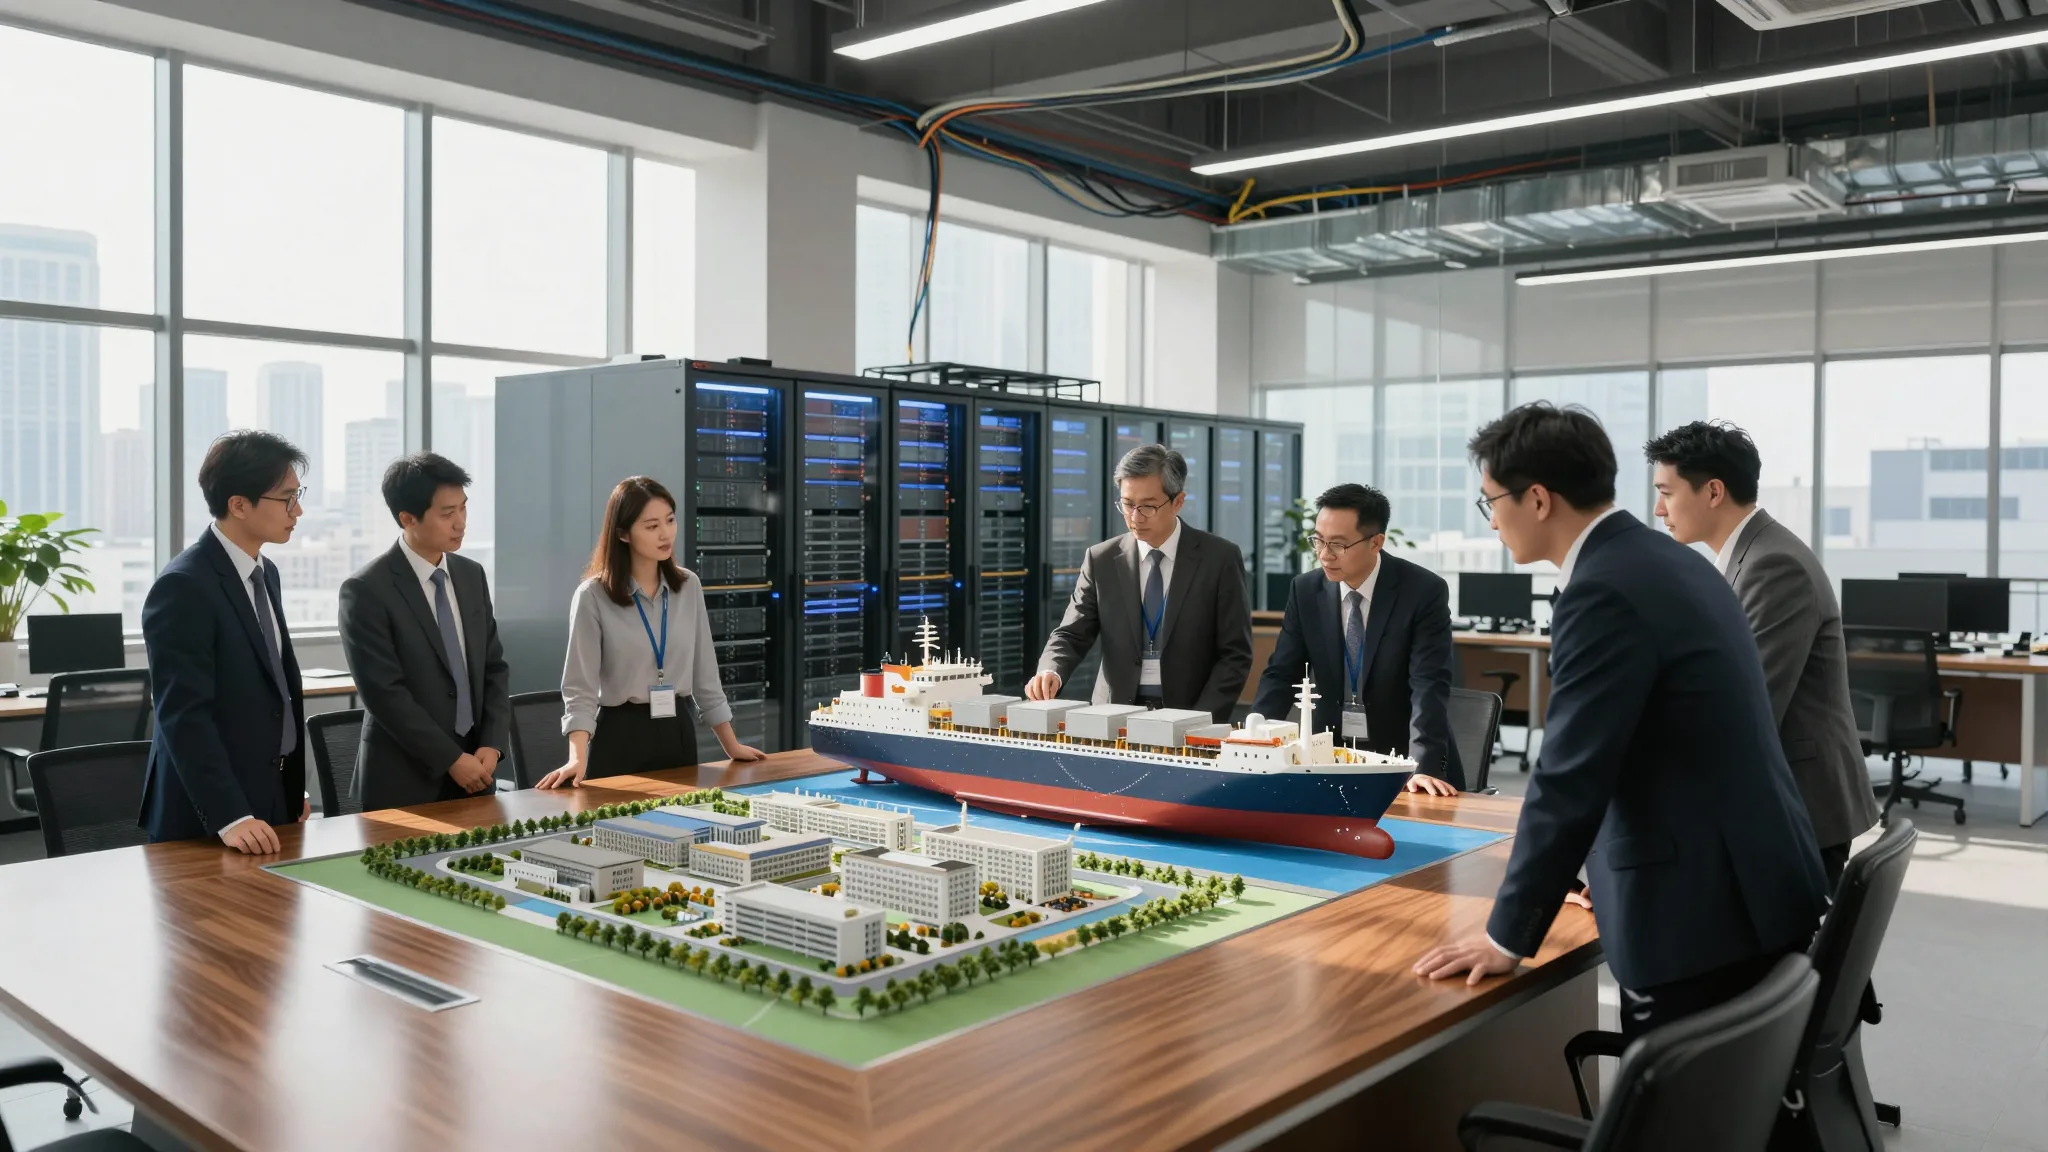
It is important to clarify that RWA tokenization does not mean moving every asset on-chain. Instead, it targets asset categories with poor liquidity, high fragmentation costs, and slow cross-border settlement for structural restructuring. Scenarios such as shipping, commodities, real estate income rights, private credit, and bond notes benefit first, because they naturally suffer from information asymmetry and long intermediary chains. On-chain transparency and programmable settlement can directly compress time costs. Understanding this helps avoid misinterpreting tokenization as a simple ‘token issuance’ action.
Why RWA Tokenization Is Accelerating in the Crypto Space
From the perspective of driving factors, the increasing acceptance of on-chain yields by institutional capital is the primary push. The stablecoin market has already surpassed two hundred billion dollars, providing a liquidity base for on-chain settlement. At the same time, major payment service providers and banks have begun including tokenized assets in pilots, signaling that traditional financial infrastructure is opening interfaces for RWA. Second, the maturation of compliance chains and sidechain technology allows asset issuers to maintain KYC/AML capabilities while gaining on-chain auditability, addressing the earlier institutional concern that ‘on-chain means anonymous.’
In addition, real pressures on the asset side are also driving change. Industries such as shipping, commodities, and private credit have long capital lock-up cycles, and traditional share transfers often take weeks. Tokenized shares, however, can be transferred within hours or even minutes under compliant conditions. For issuers, this means redesigning financing rhythms and exit paths;
for investors, it means finer position management and lower participation thresholds. The combination of these factors has turned RWA tokenization from an ‘optional experiment’ into a ‘structural trend.’
Practical Steps from Asset Selection to On-Chain Issuance
First is asset selection and legal structuring. Not all assets are suitable for tokenization. Teams should prioritize asset categories with clear ownership, predictable cash flows, and mature valuation models. Legally, SPVs (special purpose vehicles) or trust structures are commonly used to isolate risk and clarify the mapping relationship between token holders and underlying asset rights. This step determines whether subsequent compliance reviews can pass smoothly.
Next is token design and on-chain implementation. Teams need to determine token type (equity, income rights, or share-based), total issuance, lock-up and release mechanisms, and transfer restriction logic. At the smart contract level, modules such as transfer restrictions, whitelisted addresses, redemption clauses, and dividend distribution must undergo formal verification and third-party audits to avoid logic flaws that could lead to misalignment of asset rights. The third step is custody and oracle integration. Actual custody of the underlying assets is usually handled by licensed custodians, while off-chain data is synchronized on-chain through trusted oracles to ensure consistency between on-chain status and off-chain assets.
Where Are the Common Risks and Compliance Boundaries in RWA Tokenization
First is legal classification risk. Different jurisdictions classify tokens very differently. The same token may be considered a security in one region and a commodity in another, so multi-jurisdiction legal opinions must be obtained before cross-border issuance. Second is custody and settlement risk. The ‘transferability’ of on-chain tokens does not equal the ‘deliverability’ of the underlying asset. If the underlying asset has defects or the custodian defaults, the value of on-chain shares can quickly decline. There is also smart contract risk. Although audit processes are mature, edge cases, upgrade permissions, and multisig management remain common attack surfaces.
Regarding compliance boundaries, teams need to focus on investor suitability management, information disclosure obligations, anti-money laundering and sanctions screening, and cross-border data transfer rules. It is recommended to establish long-term collaboration with licensed legal advisors before issuance, rather than adding compliance documents after launch. For projects targeting institutional investors, teams should also communicate listing standards with exchanges or market makers in advance to avoid a lack of liquidity outlets after token issuance.
What Are the Most Common Pitfalls When Implementing RWA Tokenization
The most common problem is ‘launch first, comply later.’ Teams, eager to seize a time window, skip legal structuring and investor suitability processes and issue directly. As a result, they may be required to delist or buy back tokens during later financing or sales stages, causing reputational and financial losses that far exceed the time saved initially. The second pitfall is equating tokenization with ‘disintermediation.’ In reality, on-chain tokenization does not eliminate necessary intermediaries such as custody, valuation, and legal services;
it only changes how intermediaries collaborate and settle. Teams that try to bypass intermediaries entirely often underestimate operational complexity.
The third pitfall is neglecting liquidity design. If there is no market-making arrangement, secondary sales channel, or redemption mechanism after token issuance, share prices can quickly decouple from the underlying asset, creating ‘zombie tokens.’ Therefore, teams should plan liquidity solutions during the design phase, including initial market-making depth, secondary trading venue integration, and redemption trigger conditions under extreme market conditions. Ultimately, the success of RWA tokenization depends not on how sophisticated the on-chain code is, but on the degree of coordination across legal, operational, technical, and market dimensions.
Bitcoin has moved sharply lately, so the upside and the risk need to be measured together.
Checking network fees and platform rules before a transfer is especially important for beginners.